
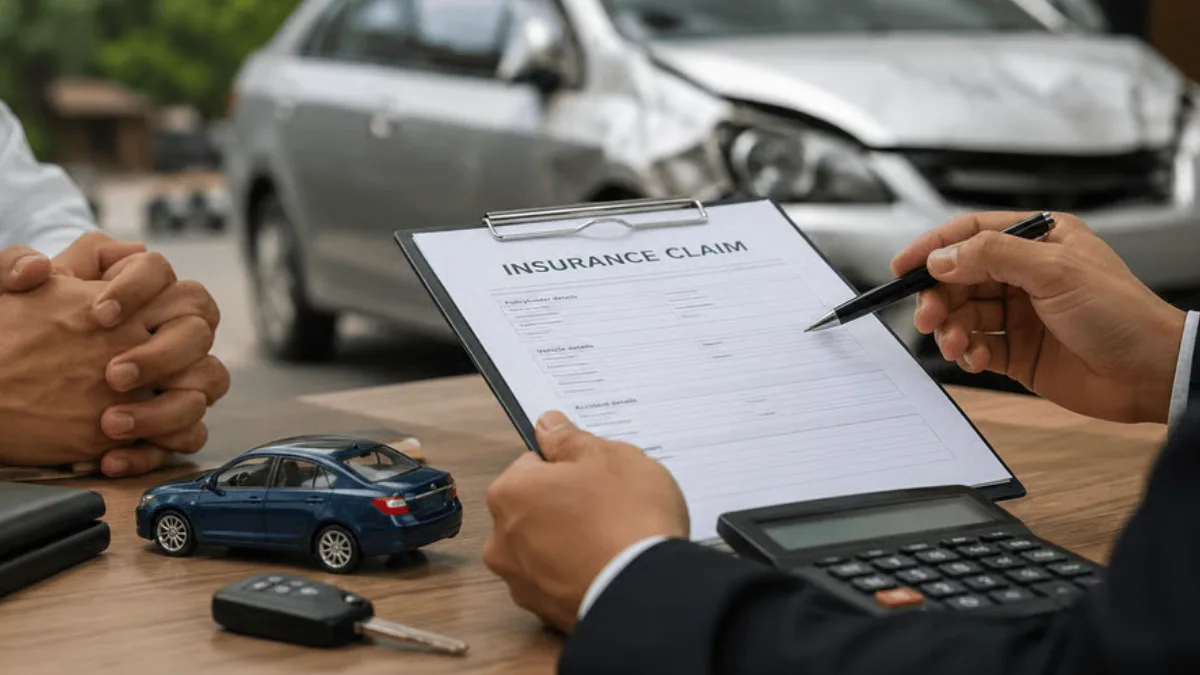
A rejection letter should tell you why the insurer turned down your claim and which policy terms they relied on. Read it carefully and compare it with your policy documents. If you do not agree with the decision, write to the insurer and ask them to review it.
You can also take a dispute over car insurance claims to the regulator’s grievance channels or to the Insurance Ombudsman, if certain conditions are met.
Knowing each step helps you send the right details and keep track of deadlines. Begin with the insurer’s grievance process, then consider further escalation based on its response.
What Should You Check Before Challenging a Claim Rejection?
For car insurance claims, a focused complaint should address the insurer’s explanation directly.
| Document or Record | What to Check | Why It Matters |
| Written Rejection Letter | Stated reason and the policy clause cited | Establishes the decision being challenged |
| Policy Schedule and Wording | Coverage, exclusions, endorsements, and relevant add-ons | Identifies the provisions applicable to your claim |
| Original Claim Submission | Incident date, description, and information provided | Helps identify factual discrepancies |
| Supporting Evidence | Photographs, estimates, invoices and relevant reports | Supports your explanation of the incident and loss |
| Previous Correspondence | Document requests, replies and acknowledgements | Establishes what was submitted and when |
How Do You Escalate a Rejected Claim to the Insurer?
Submit a written complaint to the insurer’s Grievance Redressal Officer (GRO), explaining the rejection and your grounds for disagreement. This creates a formal record of your request for review.
- Prepare a Complete Written Complaint
Follow these steps when escalating disputed car insurance claims:
- Find the Official Contact: Locate the GRO’s details on the insurer’s website or within your policy documents.
- Identify the Policy and Claim: Include your policy number, claim reference, contact details, and rejection date.
- Summarise the Events: Present the incident, submission, and rejection in chronological order, using relevant dates.
- Address Each Rejection Reason: Explain your disagreement and attach evidence corresponding to every disputed point.
- Request a Specific Remedy: State the action sought and ask for a written response explaining the review outcome.
- Record the Response and Relevant Dates
- Save the Acknowledgement: Retain the complaint reference and proof of submission.
- Track the Resolution Period: The insurer’s grievance resolution period is 14 days.
- Preserve the Final Reply: Keep the insurer’s response alongside your complaint and supporting documents.
For car insurance claims, distinguish complaint handling from claim assessment. Also distinguish the grievance resolution period from the Ombudsman’s separate one-month non-response condition.
The grievance resolution period does not guarantee claim payment within that period.
When and How Can You Escalate the Complaint Through IRDAI?
If the insurer’s response is unsatisfactory, or your complaint remains unresolved, you can use the regulatory grievance mechanism. The Insurance Regulatory and Development Authority of India (IRDAI) provides this through Bima Bharosa.
- Register Your Grievance Through Bima Bharosa
Use the following steps to record unresolved disputes involving car insurance claims:
- Visit the Official Portal: Open Bima Bharosa and follow its registration instructions.
- Enter the Relevant Details: Identify the insurer, policy, claim, and earlier written complaint.
- Explain the Unresolved Issue: Describe the response received and the points that still require attention.
- Attach Supporting Records: Include your complaint, rejection letter, insurer’s response, and relevant evidence.
- Track Further Action: Save the registration reference and review updates through the portal.
- Understand the Purpose of This Escalation
- Complaint Routing: Bima Bharosa sends the grievance into the insurer’s system and IRDAI’s repository.
- Regulatory Monitoring: The platform enables monitoring of grievance handling across insurers.
- Complaint Tracking: Policyholders can review the status of their registered grievances through the platform.
Bima Bharosa does not charge complainants. Registration does not guarantee payment or reversal of the insurer’s decision.
When Can You Approach the Insurance Ombudsman, and How Do You File?
You must first make a written representation to the insurer. Eligible disputes involving car insurance claims can then reach the Ombudsman following an unsatisfactory response or the prescribed non-response period.
- Check Eligibility and Filing Deadlines
Review these conditions before preparing your submission.
| Requirement | Applicable Condition |
| Initial Complaint | First make a written representation to the insurer |
| Rejected or Unsatisfactory Representation | You may approach the Ombudsman after receiving the relevant decision |
| No Reply | You may approach after one month without a response |
| Filing Deadline | Generally within one year of the relevant decision or expiry of the one-month response period |
| Monetary Limit | The applicable limit under the Ombudsman framework is ₹50 lakh |
| Other Proceedings | The same dispute must not be pending before, or already decided by, a court, consumer forum or arbitrator |
These conditions determine access to the Ombudsman process. Prior completion of Bima Bharosa escalation is not a listed prerequisite.
- Submit Your Complaint and Supporting Evidence
- Find the Right Office
Check which Ombudsman office covers your area on the Council for Insurance Ombudsmen (CIO) website.
- Fill In the Complaint
Say which decision you are disputing, what happened, and what outcome you want.
- Attach Your Letters With the Insurer
Add the complaint you sent to the insurer and their reply, if you received one.
- Upload Supporting Documents
Include your policy papers, ID proof, and anything else that backs up your case.
- Provide Supporting Documents: Upload policy records, identity documents, and evidence relevant to the dispute.
- Retain the Reference: Save the complaint acknowledgement and respond to further information requests.
Keep one complete complaint file and identify the next action required, including its deadline. Online insurance brokers like Jio Insurance Broking Ltd. may assist with car insurance claims queries for policies purchased through them. Its published assistance applies to policies sourced through the broker.
Also Read: 10 Tips to Choose the Right RFID Card Supplier in the UAE Without Costly Mistakes
Car Insurance Claim Rejected? How to Escalate to the Insurer, IRDAI and the Ombudsman

Car Insurance Claim Rejected? How to Escalate to the Insurer, IRDAI and the Ombudsman
A rejection letter should tell you why the insurer turned down your claim and which policy terms they relied on….
Dynamics 365 Migration: Thinks to Know Before a Single Record Moves
Most migration projects do not fail because the tooling is weak. They fail because the team treated the move as…